Shopping
Buy Now, Pay Later Services
Shoppers want to make orders easily and conveniently. That's why retailers strive to have multiple payment choices in their outlets and online stores
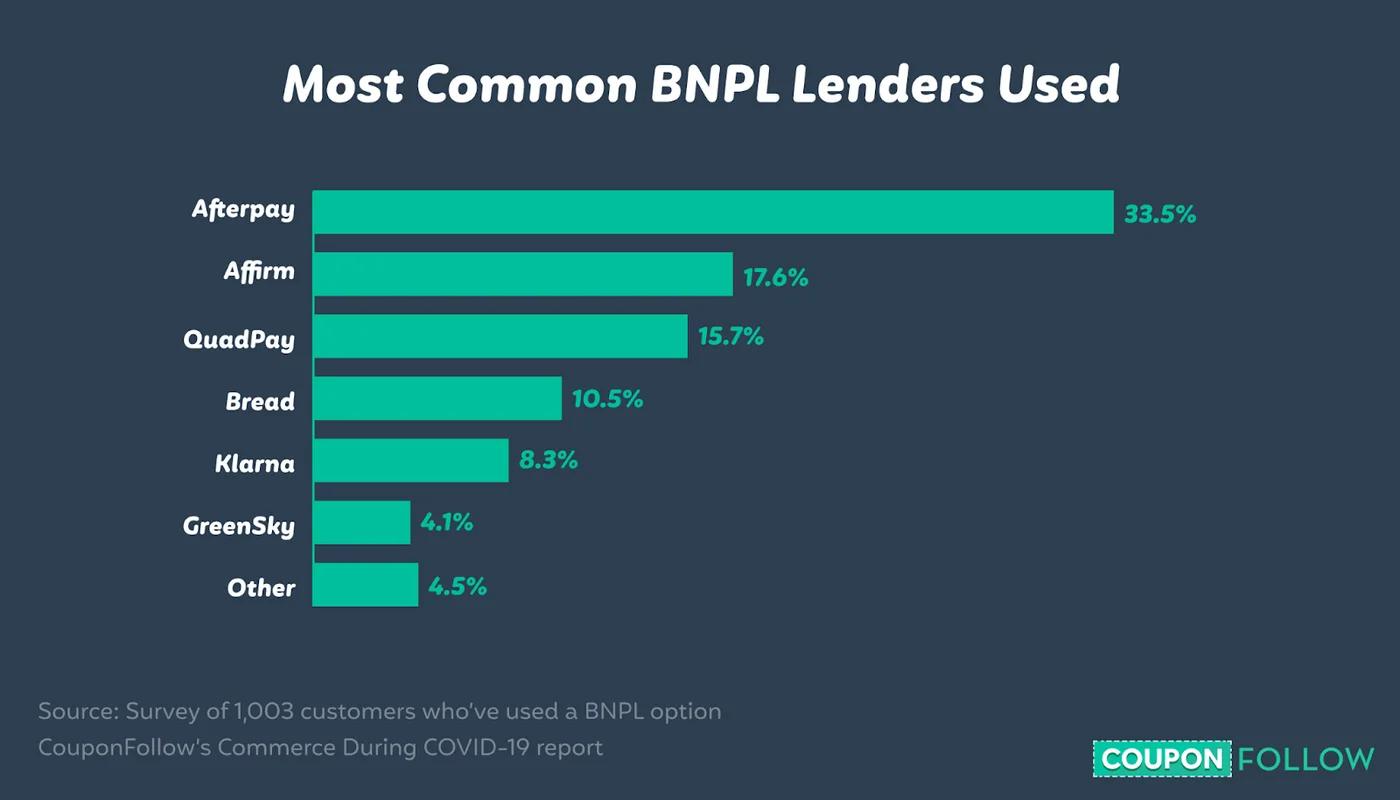
Credit cards and mobile wallets are the dominant e-commerce payment methods, with each holding a 30% market share. However, Buy Now, Pay Later (BNPL) solutions are rising with a 2% market share in the United States.
The BNPL lending market was estimated to be worth a few billion US dollars in 2019, but this is forecasted to grow by 1,200% by 2024.
The growth of any market is often because of the rise of multiple solid individual players. This is true for BNPL solutions, as shoppers have a few key choices to look at today.
This article dives deep into the best Buy Now, Pay Later sites offered today and discovers their good and bad traits. At the end of it, you'll understand what the different BNPL sites are about and how they work, so you’ll be better positioned to pick the most suitable BNPL choice for you.
What is a Buy Now, Pay Later service?
The Covid-19 pandemic affected many global operations, but a few winners emerged from it. Because of financial uncertainty and the tendency of shoppers to be cautious with their spending, Buy Now, Pay Later loans became popular, with many retailers adding them as a payment choice.
A Buy Now Pay, Later service is an arrangement that lets shoppers purchase goods and pay for them in installments. It's offered for in-store and online orders, depending on the retailer.
Essentially, shoppers buy the goods on credit but spread the payment over a certain period, often interest-free. They pay a down payment at the point of purchase and take the goods with them — a key selling point of this service.
From the retailer's end, the entire model works like this:
- A BNPL firm partners with a retailer.
- The retailer lists the specific BNPL service as a payment choice.
- Shoppers visit the retailer's store (online or physical) to purchase goods, and they select the BNPL choice as payment during checkout.
- Payment is completed; the shopper takes the goods and pays for them in installments.
While all BNPL services share this basic model, the individual terms and conditions are different. They all allow you to take goods at the point of purchase and pay for them as time passes, but the costs of applying the service, how the installments are spaced out, and potential penalties vary.
Because of this, pay attention to the specific terms and conditions of any BNPL service before you use it at checkout. We'll break down the top BNPL services offered today and their defining features to help you select a suitable one.
Best BNPL services
The growth in popularity of BNPL services has led to a surge of players in this niche. Shoppers looking for the best service can easily be confused by the wealth of choices and land on an unsuitable one.
Let’s break down the top BNPL sites.
Affirm
Affirm was among the first BNPL services to show up in the market with its inception in 2012. It started as a financial technology business branching from a startup studio and launched its consumer lending service in October 2017.
(Image source)
Today, Affirm has been used to complete 17 million orders, with $0 in late fees charged to shoppers.
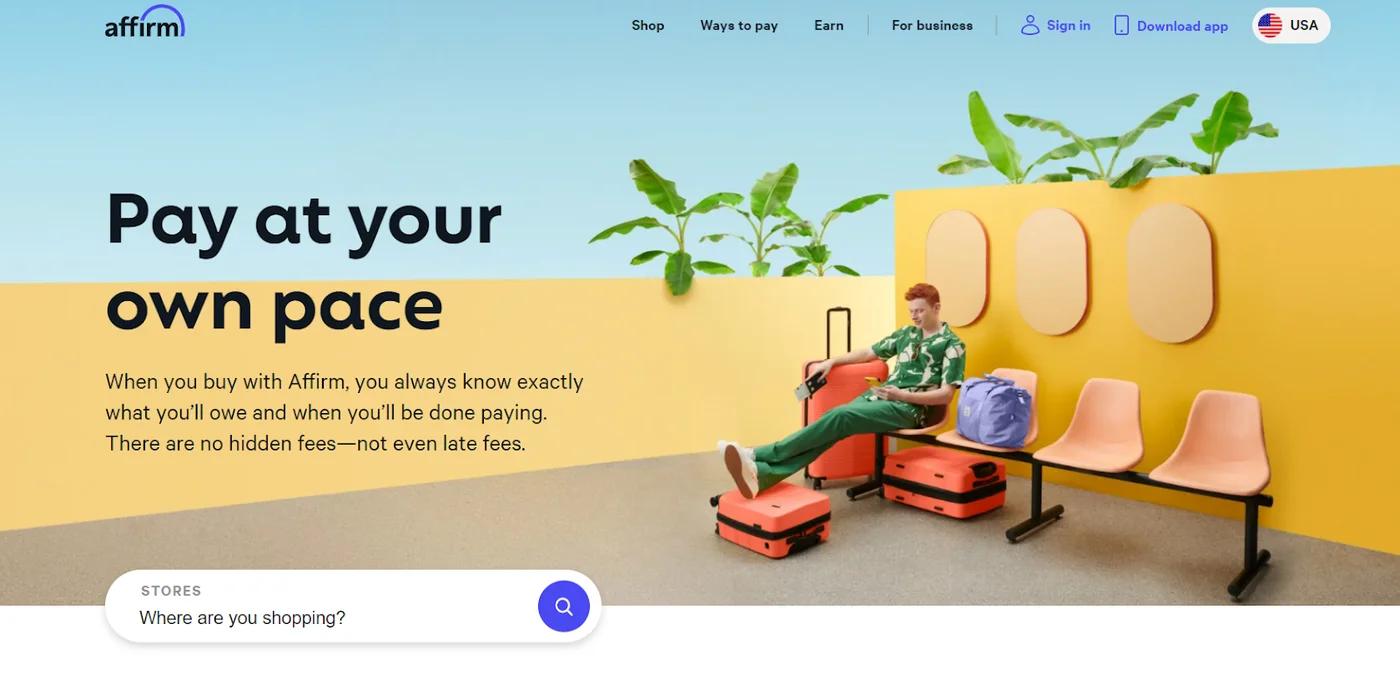
This BNPL service's main selling point is that they give you an accurate picture of what you owe and when you'll pay the outstanding installments with no hidden fees.
You can choose Affirm as the preferred payment choice in multiple eligible stores across the United States.
The different payment choices offered at Affirm include:
- Applying for a purchase loan whose payments are spread out over a 3, 6, or 12-month period, with a provision for extended periods under certain circumstances.
- Buying goods and making four equal payments every two weeks.
- Applying for an Affirm loan loaded on a virtual card and applying this to pay for orders in most online and physical stores.
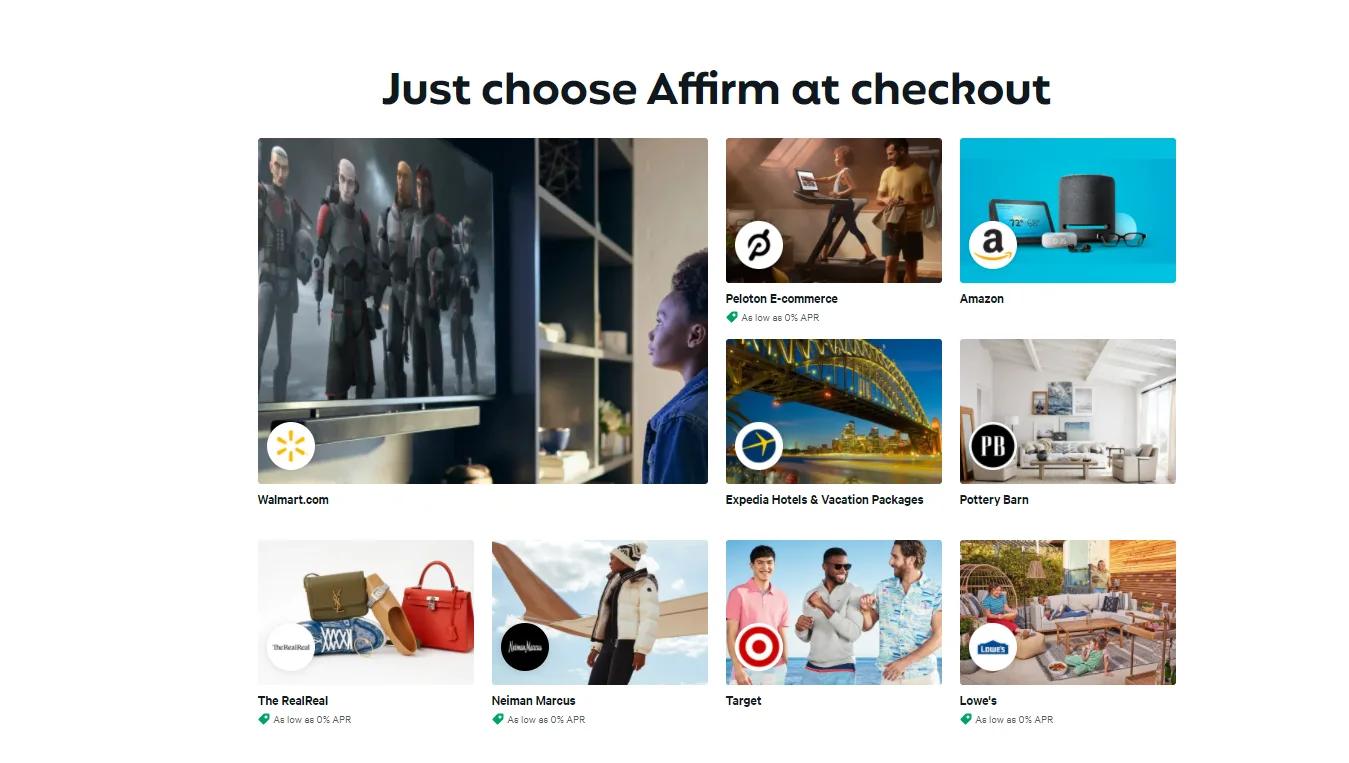
Affirm negotiates with retail outlets individually, explaining why the APR on orders varies. A few stores charge as low as 0% APR on select orders.
(Image source)
To check if your preferred store is supported by Affirm, you can search their retailers on their homepage. You'll also see if it's among the ones that offer 0% APR.
You do have to hold an account with Affirm to use their service. Signing up for one is easy and can be completed at the point of purchase, but it's safer to create one before you shop.
Affirm runs a brief credit check to determine how much you qualify for, which helps you avoid any surprises at checkout. This eligibility check doesn't affect your credit score.
When buying with Affirm:
- Confirm that your favorite store accepts Affirm for payment.
- Shop for items and select Affirm as the payment choice during checkout.
- The loan payment choices will appear differentiated by what repayment period you want — pick a suitable one for your budget.
- Complete the payment.
- Use the Affirm app or web platform to manage your payments and see how much is owed.
If you don't want to miss payments, arrange the "Autopay" feature for a specific purchase.
Affirm Pros
- Transparent terms
- Eligibility check doesn't affect credit score
- Accepted as payment in multiple stores
- Loans offered for up to $17,500
- No late fees
- No down payment required
Affirm Cons
- APR can be as high as 30%
- Requires a soft credit check
Klarna
Klarna is a Swedish-based fintech business established in 2005. Its focus was on payment processing but now offers BNPL loans as its flagship item. It has 25 million users in the United States and 147 million globally spread out in 45 countries.
(Image source)
Klarna's BNPL choices are:
- Klarna Pay in 4: Payments are divided into four equal installments due every two weeks. There’s 0% interest, but you need to pay 25% of the total purchase amount as a down payment at the point of purchase.
- Pay in 30 days: Order goods and get a 30-day window to try them out before paying the balance at the end of the period. Only pay for what you're satisfied with and return the rest. This plan is offered with select retailers.
- Monthly financing: A partnership with WebBank where purchase payments are spread over up to 36 months, at a standard APR of 19.99%. This plan attracts no annual fees, but late payment fees of up to $35 can be applied.
For other stores not offered on Klarna's platform, you can create a virtual credit card and use it at checkout.
To enjoy these plans, sign up for an account with Klarna, where you'll see all due payments and manage them. Klarna has a loyalty program called Vibe, where shoppers earn points and get rewards for applying their service.
Klarna's Pay in 4 may attract a late fee of up to $7 if a scheduled payment isn't received within ten days.
The amount of money you are eligible for is drawn from a soft credit check done when you sign up for an account. Your personal purchase history with Klarna also determines how much you can get. The soft credit check doesn't affect your credit history since it doesn't appear as an inquiry on your report.
The long-term financing choice requires a hard credit check which appears on your report.
Klarna Pros
- Multiple loan choices offered
- Pay in 4 and 30-day financing attracts no interest
- Virtual credit card expands shopping choices
- Soft credit checks don't affect your credit report.
Klarna Cons
- Late payments attract fees
- Pay in 4 requires a downpayment
- Late payments are reported to credit bureaus.
PayPal Pay in 4
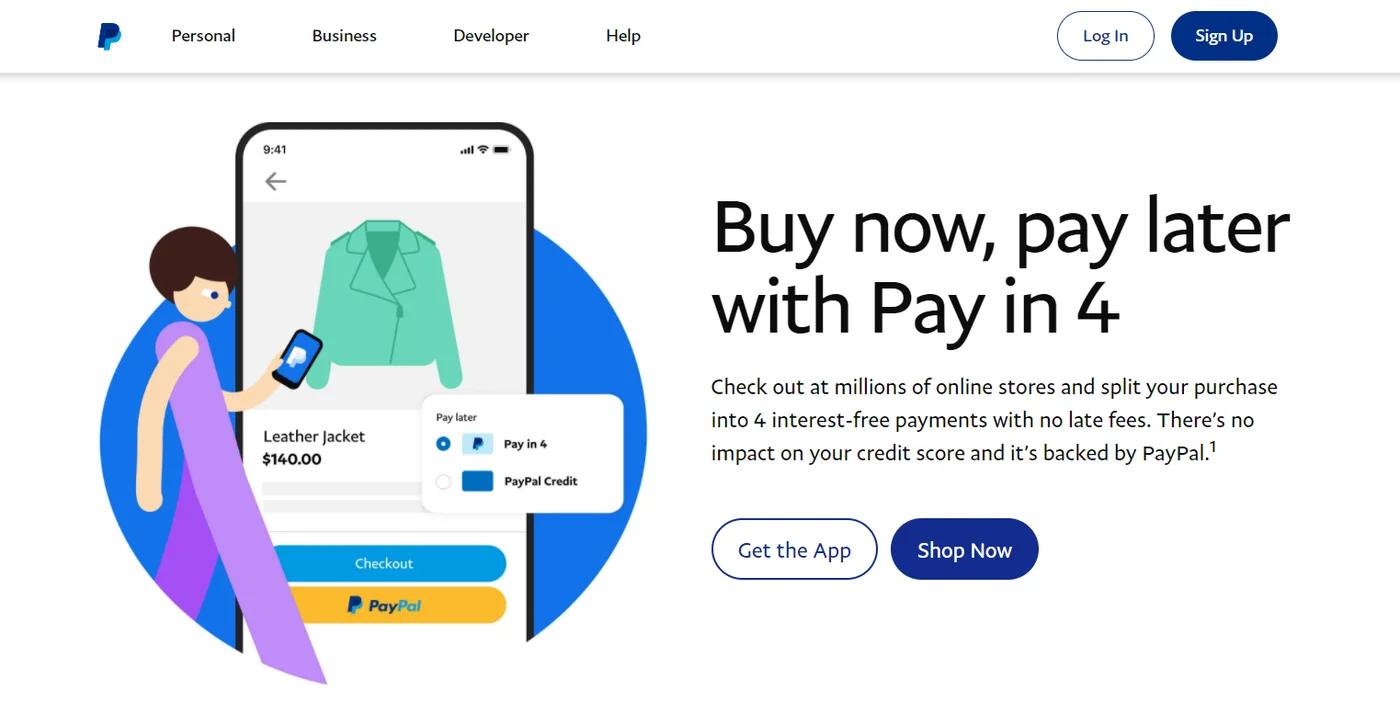
Paypal, the global payments giant, joined the BNPL bandwagon in August 2020. The item, Paypal Pay in 4, is a short-term loan designed to give shoppers a choice to spread payments for orders in 4 equal installments.
(Image source)
This service is offered to millions of online retailers for orders between $30 and $1,500. The payments are spread over a six-week period, where you pay 25% as a downpayment and the remaining installments every two weeks.
Shoppers pay no interest or fees to access this service. Payments are automated seamlessly on their PayPal account, where they can view balances and manage the loan.
Paypal Pay in 4 is a secure payment method backed by Paypal, a global leader in secure online payments. Eligible shoppers are those with a Paypal account in good standing, and Paypal also conducts a soft credit check.
Late payments attract charges that vary from state to state.
To access this BNPL loan:
- Sign up for a PayPal account.
- If you already have one, choose PayPal as the preferred payment method at checkout.
- Choose "pay later" and see how much is due after every two weeks.
- The down payment will be deducted and initial payment completed.
- Complete the remaining installments to pay off the loan.
Paypal Pay in 4 Pros
- Millions of online orders accept PayPal
- Interest-free loan repayments
- The loan is backed by Paypal
Paypal Pay in 4 Cons
- Limited loan repayment choices
- Loans are capped at $1,500
- Late payments attract a fee depending on the state.
Afterpay
Afterpay was established in 2014 in Sydney, Australia, and has become among the top BNPL services globally. It has millions of shoppers across Australia, the United States of America, New Zealand, the United Kingdom, and the European Union.
(Image source)
Over 85,000 retailers accept Afterpay as a checkout method. Their BNPL proposition is a pay-in-4 service, where shoppers can spread payments over four installments.
To use Afterpay:
- Sign up for an account on their platform. It's free, and you'll instantly know if you are approved or not.
- When shopping online, select Afterpay as the preferred checkout choice.
- Arrange a virtual card on the Afterpay App if you're shopping in-store. Use this card as you would a regular card at checkout.
Afterpay credit limits start at $500, which is the limit most new accounts get on sign-up. From here, the limit gradually increases depending on usage and how you pay back the loan.
Afterpay doesn't report your borrowing and payment history to credit bureaus. Good payment history won't improve your credit report, while late repayments won't hurt it either.
If you don't repay the loan in good time, your account will be frozen, and you won't be able to take any more loans. Late payments attract a fixed $10 fee and an extra $7 if you don't clear the balance within seven days. Late fees are capped at 25% of the total purchase amount, so small orders cannot attract huge fees.
Afterpay Pros
- No interest on loans
- Late fees are capped at 25% of the original purchase amount
- It doesn't require a credit check.
Afterpay Cons
- Charges late fees
- Limited BNPL choices.
Splitit
Splitit was established in 2012 and offers a unique proposition in the Buy Now, Pay Later space. Its item is for diligent credit card users who make all their payments in good time.
(Image source)
Unlike some other BNPL services here, it has no credit check, no interest, no charges, and no fees to use the service. The loan uses your credit card.
But how does it work?
Splitit will check if your card has enough credit to pay for the whole amount when buying goods. This is the first authorization step. If this goes through, it'll charge you the first installment. It'll then place a pre-authorization hold on your credit card for the installments you chose to pay over the said period. That hold will reduce as you pay the installments.
Assume you want to buy goods worth $800, spread over ten installments of $80 each. Splitit will check if your credit limit is above $800 and charge only $80. The remaining nine installments will appear as pending transactions on your statement, because of be completed every month.
To use it when shopping:
- Choose Splitit as the preferred payment choice at checkout.
- Select the number of installments, often between 3, 6, 12, and 24.
- Key in your credit card details.
- Complete the payment.
Split combines the best of BNPL services and credit cards since you enjoy all the benefits of applying your card to make orders, like cashback, loyalty points, and rewards.
Splitit Pros
- No late payments
- Interest-free
- No application process or credit check
- Buyers are still eligible for rewards specific to their credit cards.
Splitit Cons
- Limited payment choices
- Partners with a limited number of retailers
- Places a hold on your credit card
- Retailers determine the minimum and maximum values one can purchase applying Splitit.
Zip
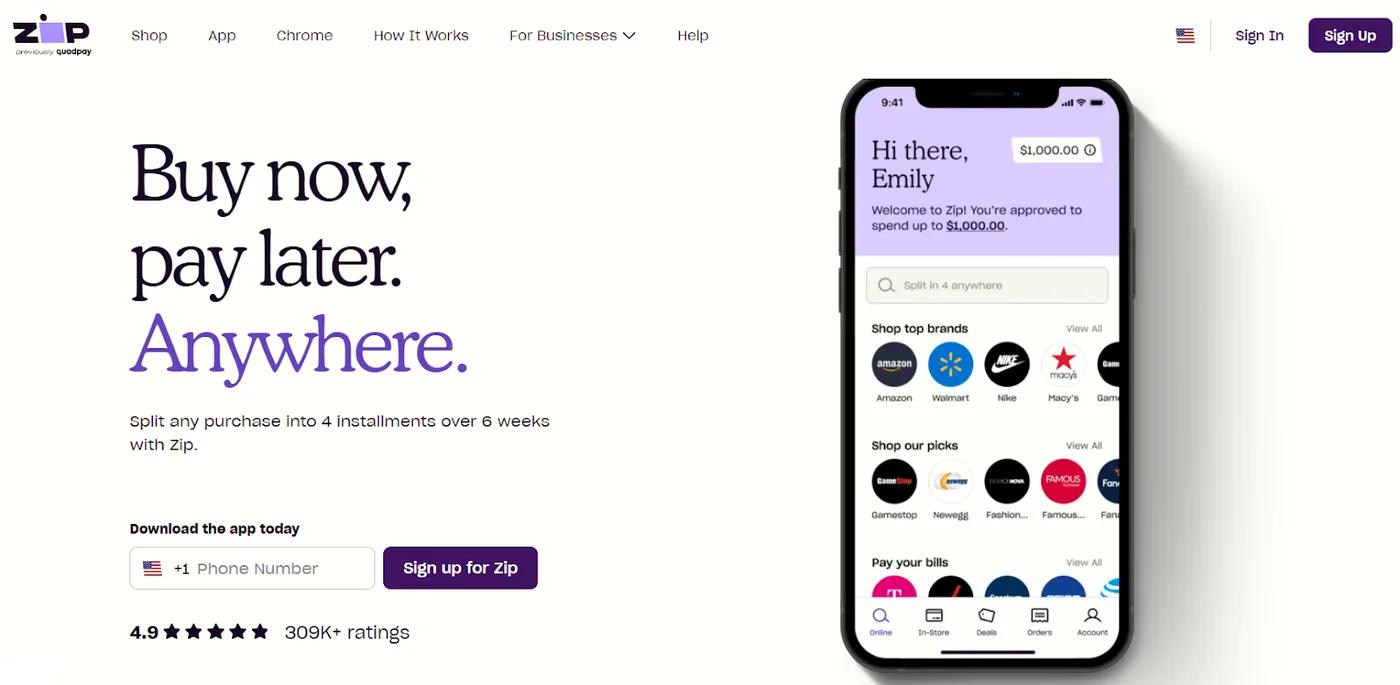
Zip, formerly Quadpay, is a financial business that operates across four countries, partnering with over 26,000 merchants.
(Image source)
It has two main items – Zip Pay and Zip Money.
Zip Pay is their BNPL service that offers interest-free payments for orders up to $1,000. Repayments start from as low as $10 per week.
Zip Money is a credit card line with limits of over $1,000. Limits go up to $5,000 for regular accounts and $50,000 for specific merchants.
Their main BNPL service, Pay in 4, splits purchase amounts into four equal installments, due every two weeks. You have to pay 25% of the total amount as a downpayment at the point of purchase and then complete the remaining installments within six weeks.
To use Zip Pay for online orders:
- Create an account on the Zip web platform or App. It'll conduct a soft credit check and determine how much you're eligible for.
- Search for your favorite store and add items to the cart on the Zip account. At checkout, select Pay with Zip.
- Confirm the total purchase amount is correct and the payment schedule is appropriate.
- Complete the payment.
For in-store orders:
- Choose the in-store tab on the App and key in the amount you're looking to spend.
- Confirm the amount and proceed to review the repayment schedule for this amount.
- Zip will generate a virtual credit card that you can add to your mobile wallet to complete orders when you buy items at a store.
The Zip app sends friendly reminders to be sure you don't miss out on any payments. Late payments attract an initial $8 penalty and a subsequent $8 penalty for every week you don't complete the payment. These charges are capped at $40.
Zip Pros
- Multiple loan choices.
- Interest-free loans.
- Zip Money offers loans for huge orders that go up to $50,000.
- Easy to sign up and get approval.
Zip Cons
- Late fees.
- Late payments are reported to credit bureaus.
Perpay
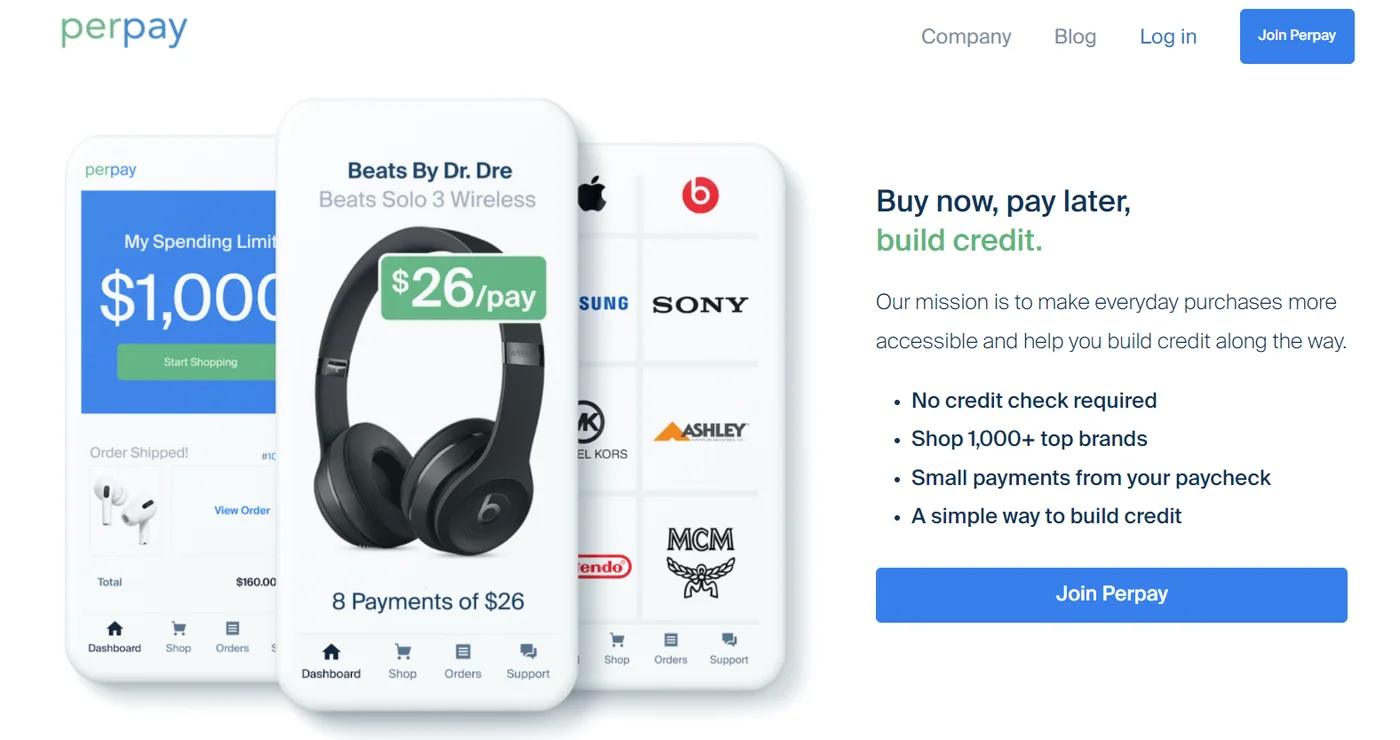
Perpay is a financial services provider established in 2014 with over 3 million shoppers. Perpay, like the BNPL services discussed so far, allows shoppers to complete orders and pay for them as time passes, but it has one key difference: it helps you build credit.
(Image source)
It belongs to a unique set of BNPL services that help you build credit. Most BNPL providers don't report timely repayments to credit bureaus.
But, as Perpay notes, timely payments can improve your credit score. Its shoppers noticed an average increase of 39 points within 6 months, which is perfect for anyone with bad credit looking to improve.
Perpay deducts payments from your paycheck, which forms the basis of the initial spending limit you get. To check the limit, upload your pay stub on the Perpay platform.
All payments are made by a small direct deposit from your paycheck, which is aligned to your pay cycle. To complete orders, you'll need to pay at least one installment. You can split payments through different accounts if you juggle multiple jobs.
Note that the credit building feature isn't offered automatically, and you'll need to activate Perpay + to access it. Also, Perpay reports payments after you complete on-time payments for four months, and they should exceed $200. Poor-performing accounts may not qualify for the credit building feature.
To use Perpay:
- Create an account to get a spending limit.
- Check the marketplace for eligible brands to shop from.
- Checkout and complete payments that go to the Perpay team for approval.
- The team sets up a Perpay deposit system over the number of installments you choose.
- The order will be processed for shipment once the first payment is made.
Perpay Pros
- Helps build credit
- Payments are deducted from your paycheck, which keeps things simple
- Net pay determines the spending limit
- No credit limit check required
Perpay Cons
- Limited to a few retailers
- Approvals aren't instant
- Not all loans qualify for the credit building feature.
Pros and cons of BNPL loans
We’ve covered some of the top BNPL services in the market today, and they share many similarities. Save for a few with different models, they all offer convenient and quick access to loans that fund orders and allow you to pay as time passes.
BNPL solutions are often compared to credit cards, which people were used to before these loans became popular. Most of their pros and cons stem from how they compare to credit cards.
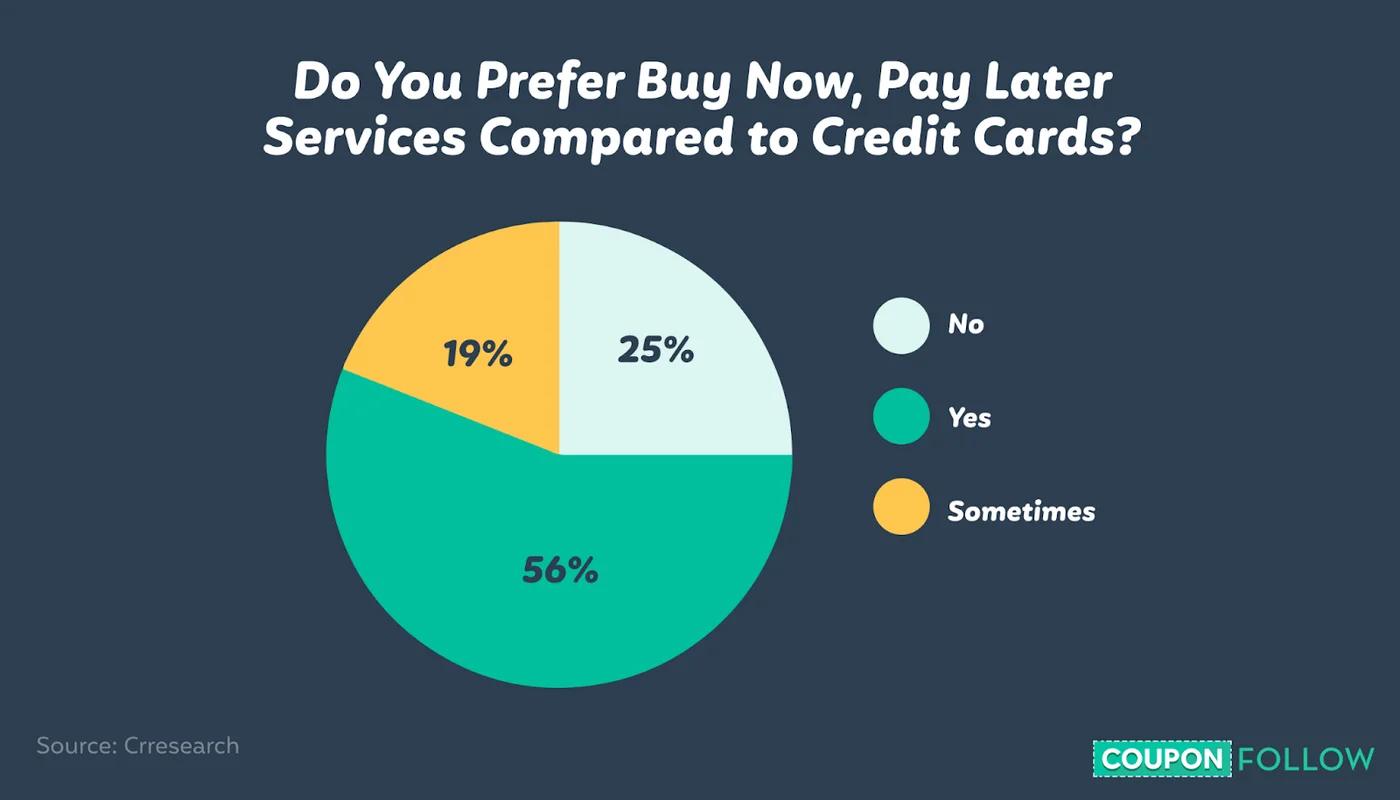
They include:
Pros of BNPL loans
- Instant access: BNPL loans are offered to shoppers at the point of purchase and offer swift approvals in minutes. Credit cards have a sophisticated application process and take longer to approve.
- Easy to use: BNPL loans are integrated with most retailers' checkout systems to make them easy to use.
- Multiple payment choices: Most BNPL services offer shoppers flexible payment choices where they can spread installments through a specific period.
- Low interest: Most BNPL loans offer some zero-interest payment choices, often for the short-term pay-in-4 plans. Other plans charge low-interest rates, which makes them a better choice than a high-interest credit card.
- No hard credit check: BNPL services are perfect for people with bad credit since the businesses don't perform a hard credit check. Most will do a soft one, with others not requiring any checks.
Cons of BNPL loans
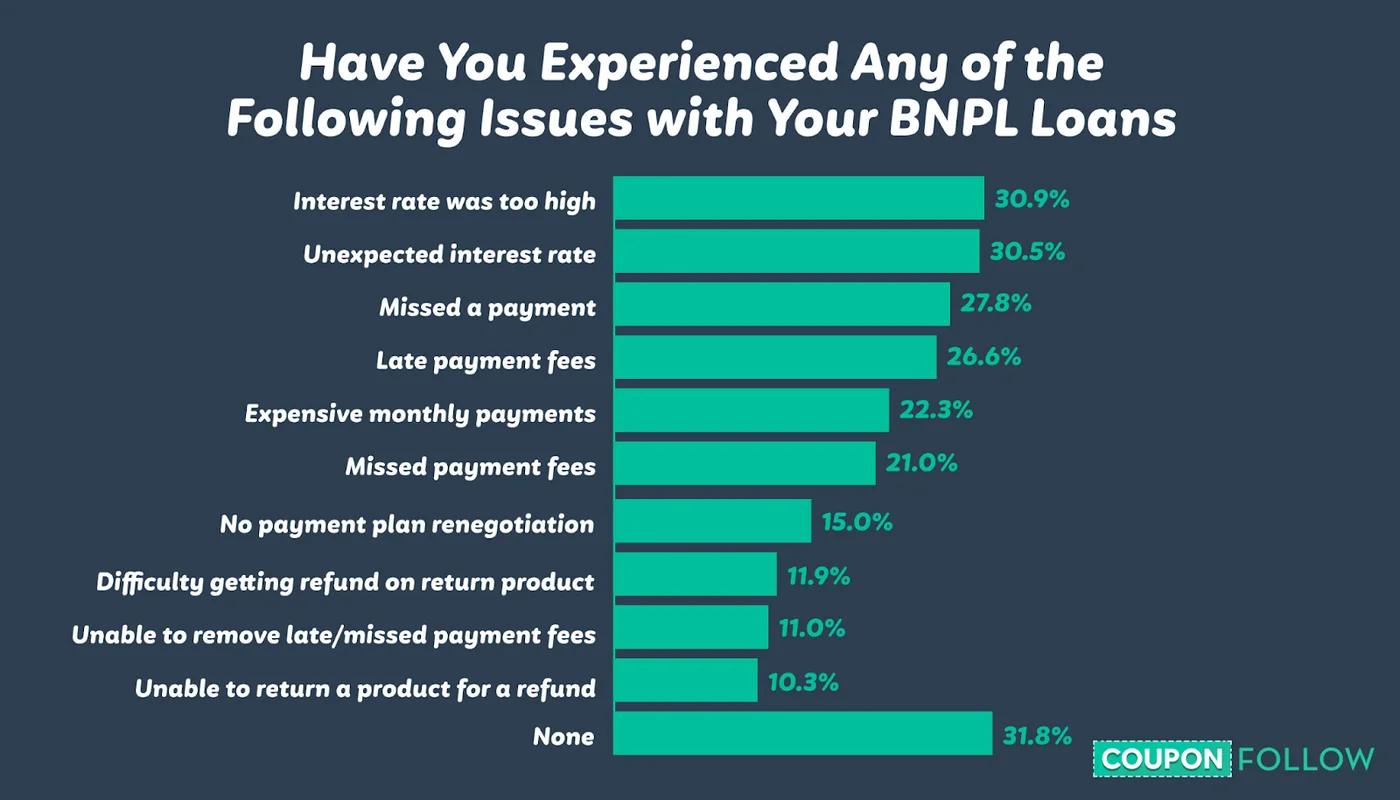
- Impact of missed payments: Missed and late payments are bad since they are reported to credit bureaus and attract late payment fees for most of these loans.
- Interest rates: Some BNPL services, like Affirm, charge a high APR of up to 30% for specific retailers, making it a costly choice.
Ways to choose the best BNPL service
The wealth of choices in the BNPL niche can make it tricky to choose between them. And your experience with these services hinges a lot on whether you pick the right one.
If you're looking to explore a BNPL service for making orders, don't rush over the fine print as there's no perfect one. It all depends on your financial situation and whether the terms of the service align with it or not.
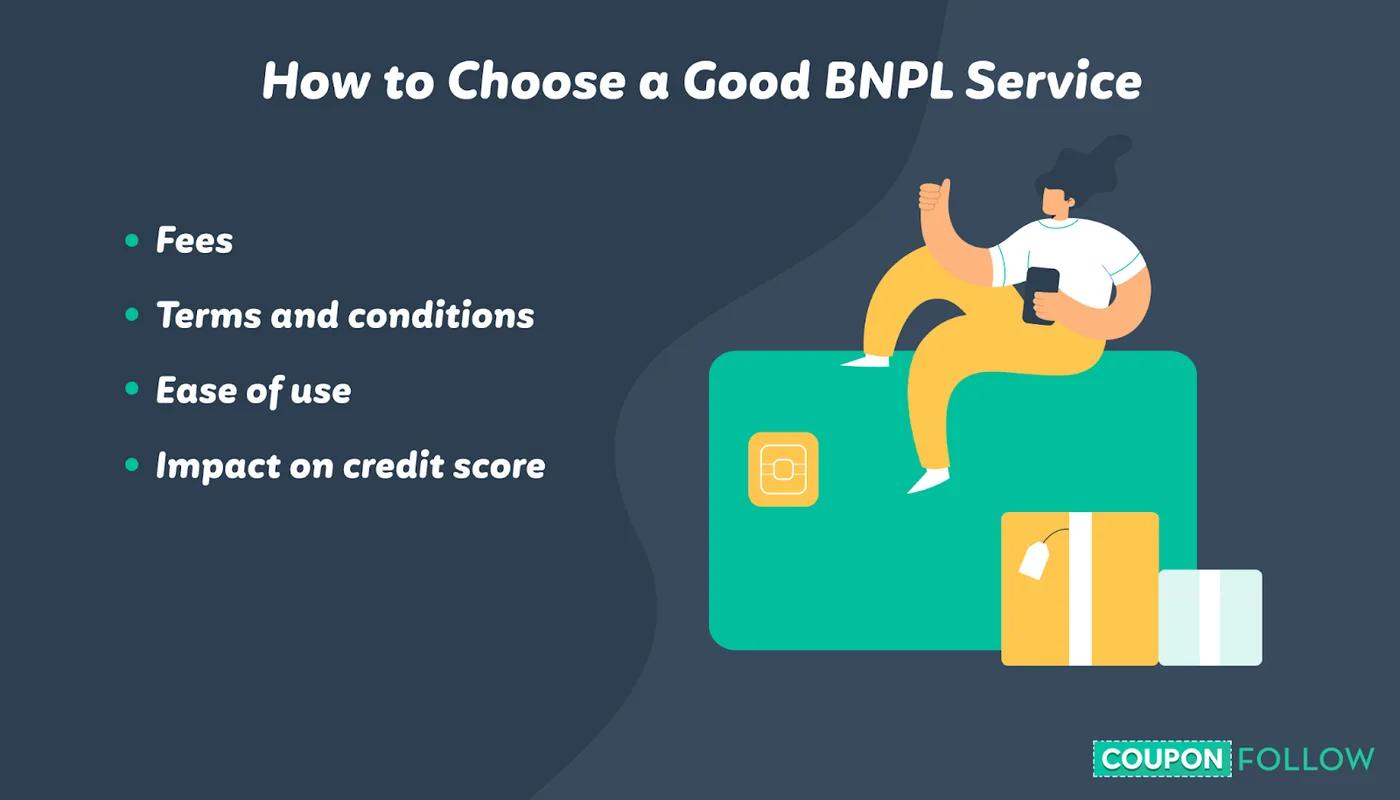
First, look at the cost of the loan. The whole point of a BNPL service is to get a less costly financing choice, so you don't want to be paying a lot to use the service. The cost goes beyond interest rates, as late repayment and processing fees associated with applying the service come into play.
Look at the service holistically and see how much you'll pay back if you borrow $1,000 of credit. Once you determine this for each provider, it's easier to see which one actually has the best cost for your budget.
Additionally, the repayment terms are critical. Look at how this works with respect to your income schedule. If you earn every week, the pay-in-4 choice might work for you, but if you earn monthly, it might not. Find a schedule that aligns with your payment schedule to avoid missed payments.
The loan period also plays a key role here.
Also, look at shopper service and ease of use. You want a loan that's accessible and has a friendly platform you can use to check and manage payment schedules.
Lastly, understand the good and bad of your preferred BNPL service, and be ready to live with the consequences. This helps you know what you're signing up for and avoid any nasty surprises.
Conclusion
BNPL services have revolutionized the retail space, as shoppers have a different choice to turn to if credit cards don't work for them. The growth of this niche will continue, and we expect to see more prominent players emerging here.
As a shopper looking for convenient and flexible ways to pay for orders, always do some digging before applying any of these services. The fine print will give you a clear picture of what you're signing up for, so don't skimp over it.
If you're looking for extra ways to save on orders, check out Sacodes for a collection of coupons you can use when shopping at your favorite retail outlets.