Money
The Buy Now, Pay Later App — Everything you need to know about Affirm
Have you ever come across something you want badly but don't have the full amount to pay for it?
Let’s face it — we’ve all been there.
The sad part is that you might have enough financial muscle to afford it but can’t do it at the moment because of circumstances like delayed paychecks or budgetary constraints.
In such instances, you could use a solution that lets you buy the item and pay for it in a few installments, like Affirm. This is particularly useful for huge orders that can easily affect your monthly budget if you pay for them in one go.
There are multiple Buy Now Pay Later (BNPL) services in the market, but most of them have unfavorable terms and conditions.
Here, we'll break down Affirm, a top BNPL service with transparent terms and a flexible repayment plan for you. Read on and learn more about Affirm to see if you qualify to make orders that allow you to spread out the payment through a few installments.
What is Affirm?
Shoppers don't have many choices at checkout when buying items. They can often either pay in cash or use their credit cards.
Credit cards are essentially loans offered by entities not related to the merchant. If you don't have money or can't organize to have a credit facility to settle the amount, you can’t buy anything.
Affirm is a Buy Now Pay Later payment service that gives shoppers an extra choice when making orders. It was launched in 2012 by PayPal co-founder Max Levchin.
BNPL solutions are loans extended to shoppers by merchants at the point of sale. They are often only used to buy specific items and services.
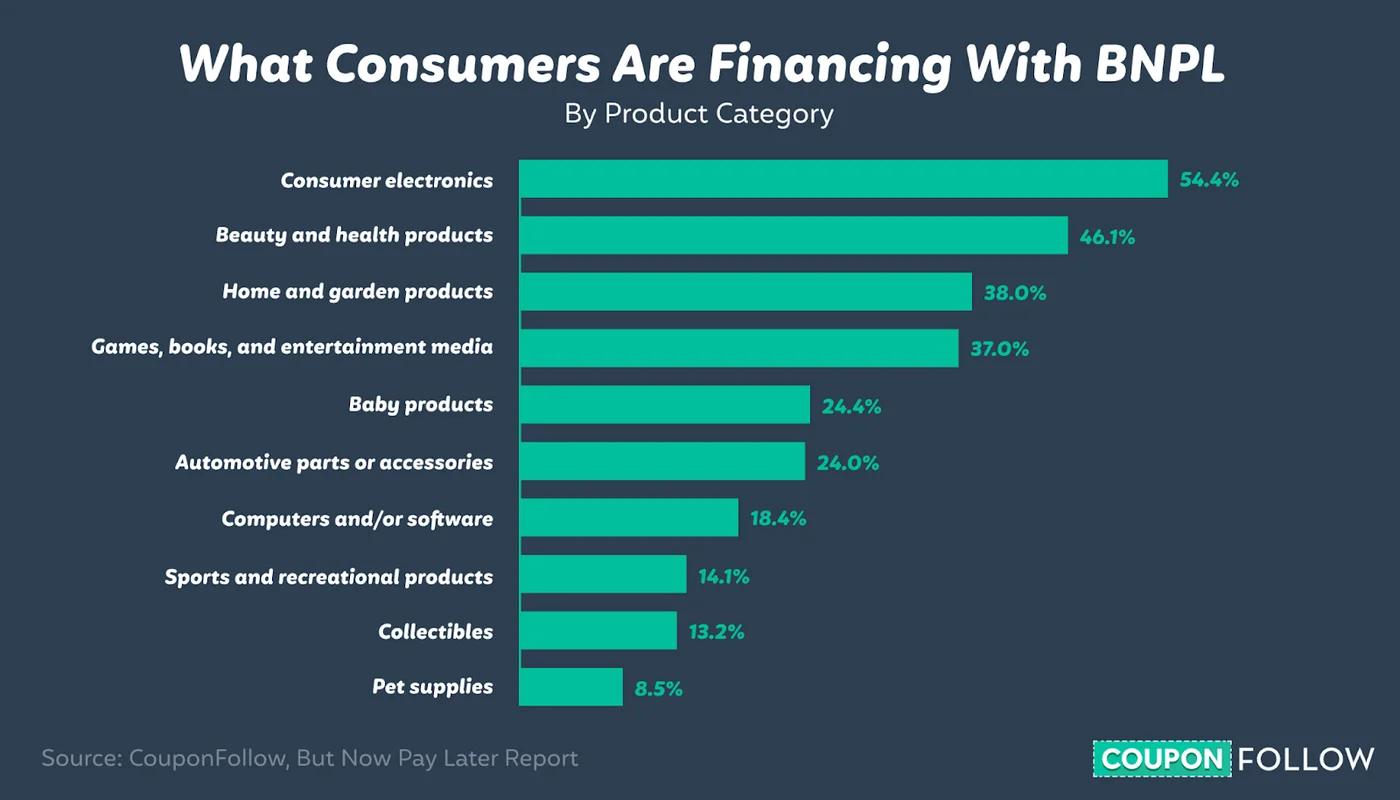
The COVID-19 pandemic brought about economic uncertainty that fueled the growth of this payment choice. A survey indicates that about a third of U.S. shoppers have used a BNPL service, and 81% of them are likely to use one again.
Shoppers are taking up this solution for a mix of reasons, as seen from the types and goods and services they are buying applying it:
With Affirm, you can buy any qualifying commodity and spread the payment over a few months. The interest rate is fixed upfront, and you clearly know the exact amount due every month.
How does Affirm work?
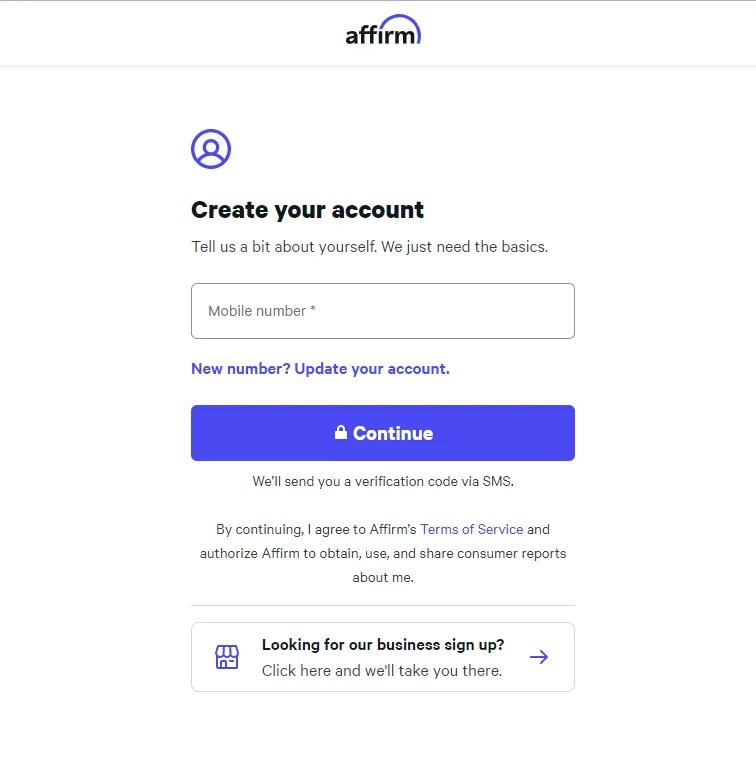
You need to have an account with Affirm to use it as a payment choice.
(Image source)
Signing up is easy, as you can do it on their site. You must meet the following qualifications:
- Be over 18 years old.
- Provide a valid U.S. home address.
- Provide a working U.S. phone number.
- Provide your full name, last four digits of your Social Security number (SSN), and date of birth.
The phone number should be registered in your name, and you’ll be sent a SMS message to verify this.
On successful registration, log on to the Affirm app or through a browser. Here, you'll view your account details, like any outstanding loans and completed payments.
Affirm partners with select retail outlets to have it as a payment choice. If you are shopping in one of them, select Affirm as the payment choice at checkout.
Input your details, i.e., name, phone number, and last four digits of your SSN, to authenticate your account. Affirm will send a text message with a unique authorization code. Enter this code at checkout to confirm your identity.
In a few seconds, Affirm will check your account and show you how much you qualify for as a loan, the interest rate, and payment choices. Typically, you can pay off a loan in 3, 6, or 12 months.
If the offer works for you, click “Confirm Loan,” and you'll be good to go.
Affirm looks at several factors that determine if they approve or reject your loan request. They include:
- Prevalent economic conditions
- Eligibility criteria like your credit score
- Payment history with Affirm
- The interest rate offered by the specific merchant you are buying from
Interest rates are negotiated individually with each merchant. Because of this, eligible loan amounts might vary from merchant to merchant and the time at which you are sending the request.
The annual percentage rate (APR) can vary between 0% and 30%, but this will be displayed before you confirm the request. The first payment is due 30 days after completing the purchase.
To enhance transparency, Affirm sends an email explaining why they reject any loan requests.
Which stores accept Affirm?
You can only use Affirm in select stores that have an agreement with them.
With the increased uptake for these services, it is no surprise to see most major retailers joining the bandwagon and offering Affirm as one of their payment choices. Stores that offer loans from 0% stand out from the rest, as shoppers always prefer to pay less.
The main general retailers on this list are:
- Walmart
- Target
- Reverb
- Amazon
Sellers in the travel industry include:
- Expedia
- CheapTickets
- Orbitz
- CheapAir
- CheapOair
- CheapFlightsFares
- Travelocity.
Fashion retailers include:
- Faherty
- Adidas
- La Garconne
- Eddie Bauer
- Nike
- Nikki Lorenz Designs
- Gucci
- StockX
- Universal Standard
Examples of home, kitchen, and decor sellers are:
- BedJet
- Dyson
- Parachute
- Brooklyn Bedding
- Birch Lane
- AllModern
- Campaign
- Havenly
- Mirror
- Rugs.com
- The Inside
- Wayfair
- KitchenAid
Automotive sellers include:
- Auto Anything
- Goodyear
- Morris 4x4 Center
Before you buy anything with Affirm, confirm on their site if the store you want to purchase from is approved. It will indicate which ones have a 0% APR, and you can use this to find an outlet with better loan terms.
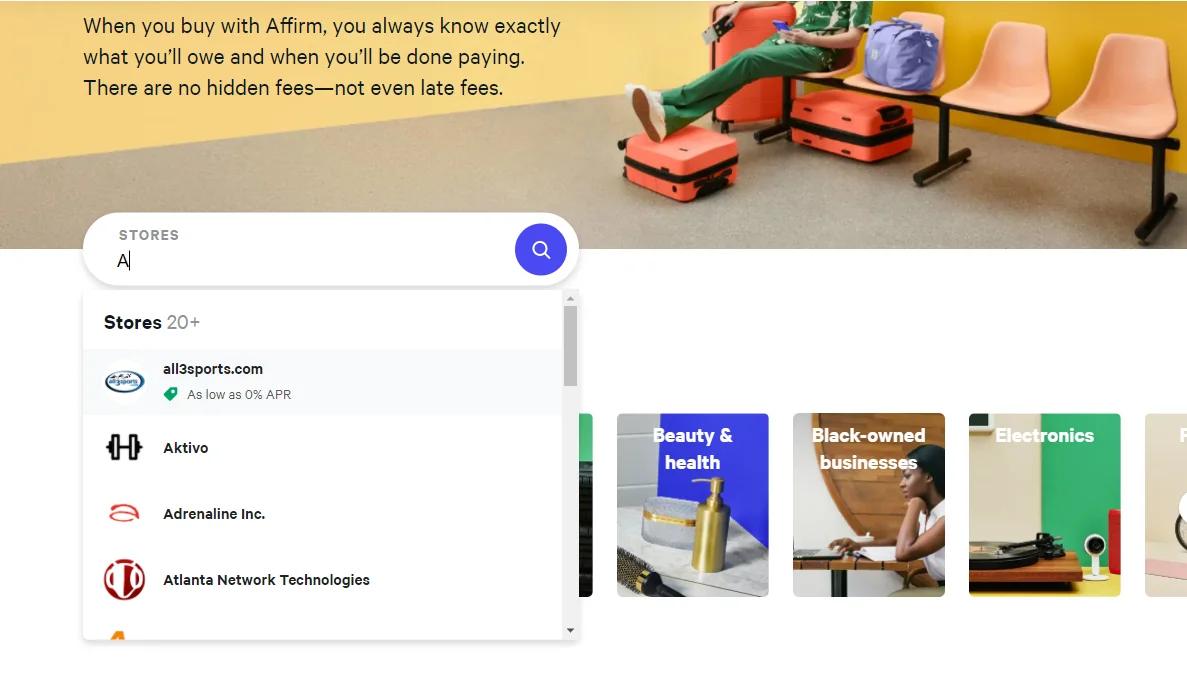
([Image Source](https://www.affirm.com/)) You can use Affirm for both online and in-store orders. For brick-and-mortar stores, the cashier will select this choice at checkout and ask for your details for Affirm to check how much you're eligible for.
What are the costs of applying Affirm?
Affirm doesn't charge any fees. There are no subscription fees, and creating an account is free.
All loan costs are transparent and shown to shoppers before they confirm. The monthly payments are fixed throughout the loan period and don't compound like credit cards.
For instance, if you take out a loan with Affirm to buy goods worth $1,000 with 15% APR, here are what your payment choices will look like:
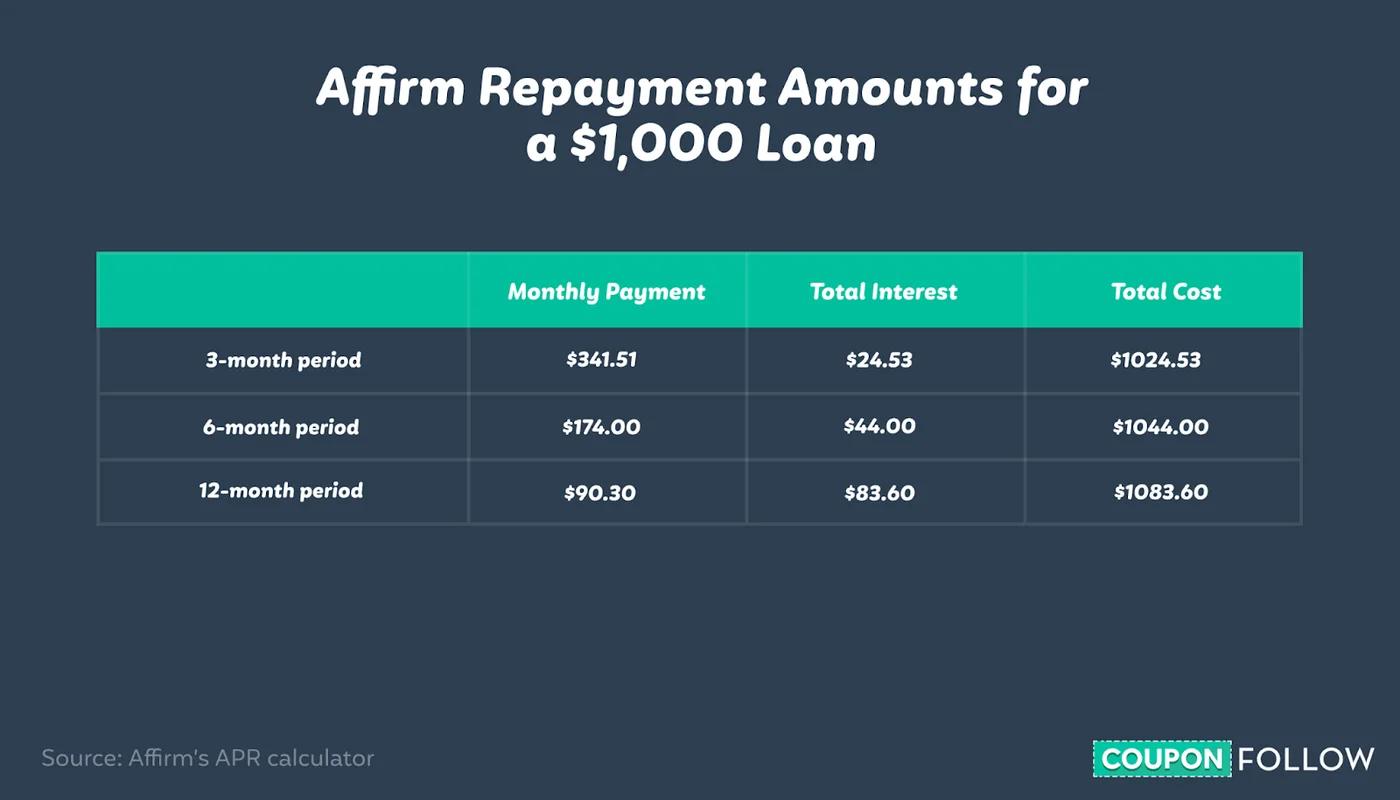
The longer the period, the higher the interest paid. From the example above, the APR is calculated and divided by the number of months to arrive at equal monthly payments.
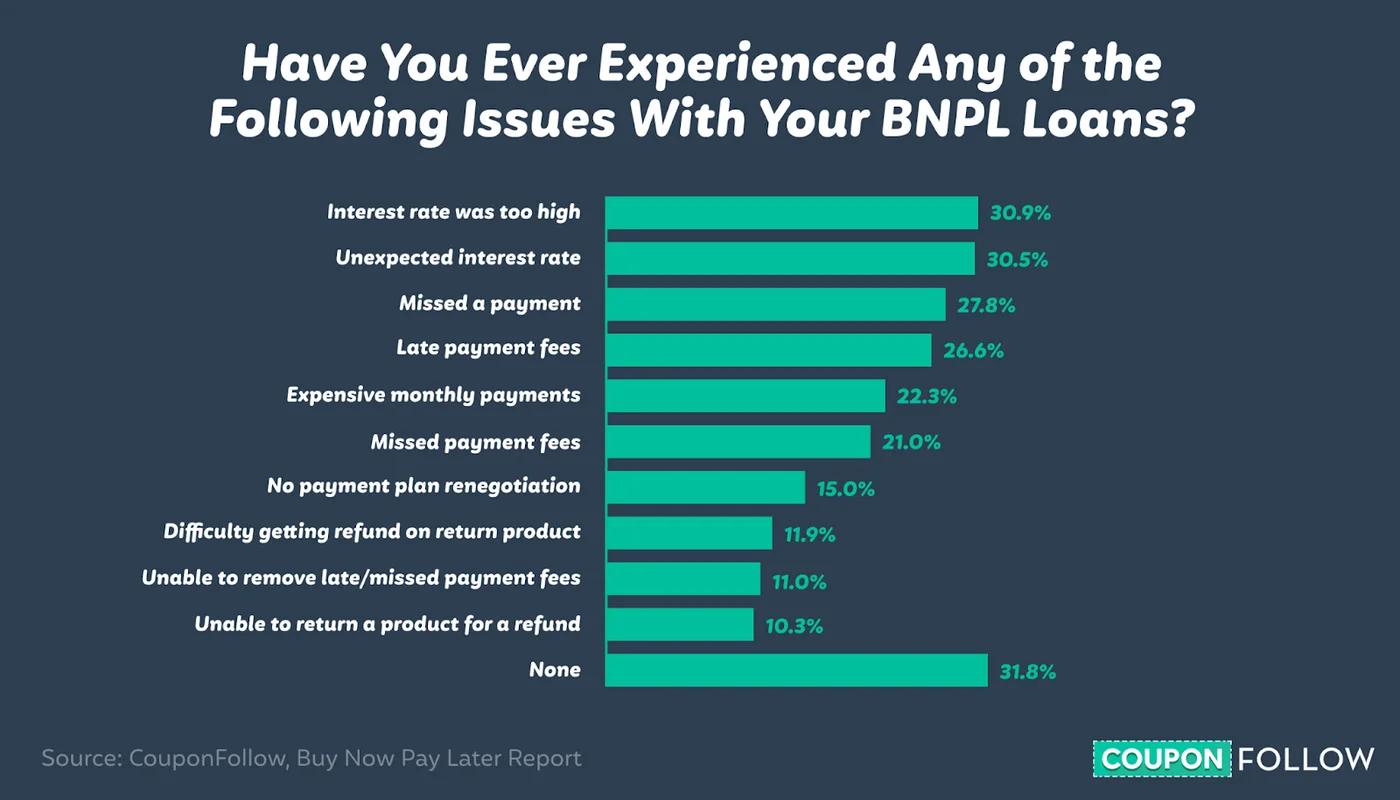
There are no late fees for missing payments. However, Affirm reports missed payments to credit bureaus, and this will affect your credit score. Also, they'll probably reject your future loan applications.
To check how much you've paid and any outstanding balance, simply log in to your account on the Affirm site or app and click on Pay. Here, you'll see all orders, and you can click on a particular one to see the remaining balance and other details.
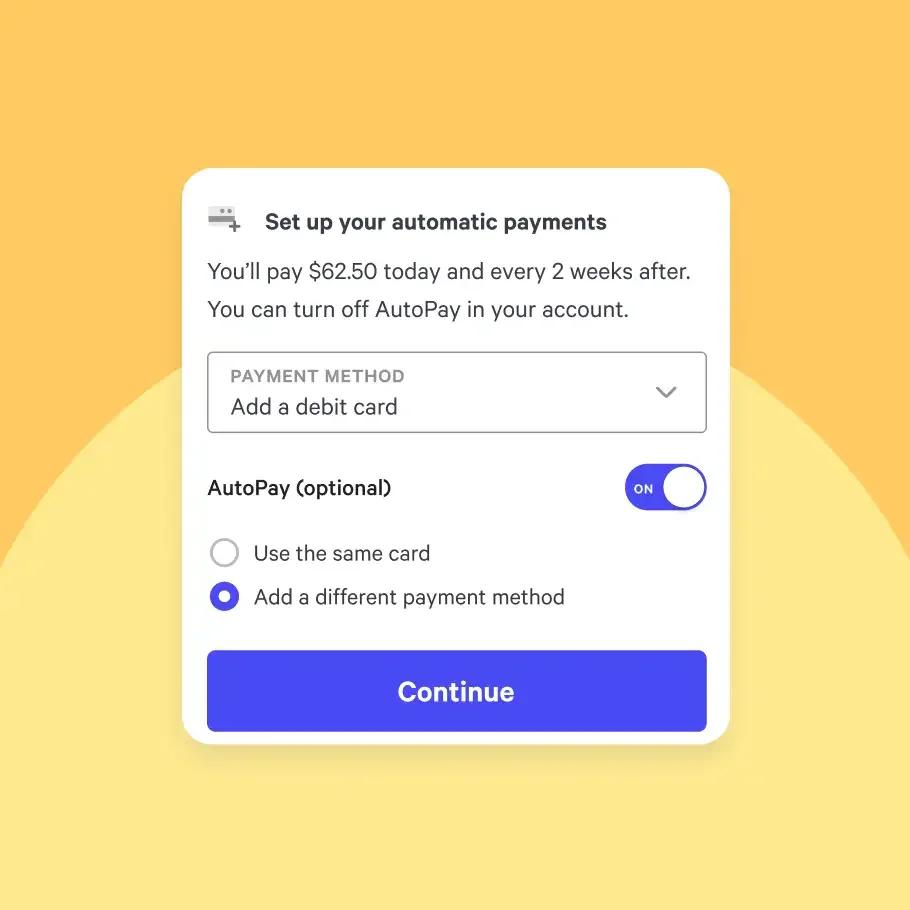
All payment methods are logged into your account. Affirm accepts multiple payment choices, including debit cards, checking accounts, credit cards, and checks. Understand that checks take about ten business days to process. Be sure you send in a payment well before the due date to avoid cases where you are flagged for late payments.
If you turn on the AutoPay feature, payments will automatically be deducted from your account. This is the best way to be sure you make payments on time. AutoPay will only deduct the monthly amount agreed upon initially and not clear overdue balances.
(Image source)
You have to make one-off payments to clear overdue balances.
What are the pros and cons of paying later with Affirm?
Let’s break down both the advantages and disadvantages of applying Affirm.
Pros of Affirm
First, let’s look at some of the pros:
1. Low APR
Affirm charges a fluid APR depending on the rates negotiated with individual retailers. Some retailers offer as low as 0% on orders. This is essentially a no-interest loan, and you only pay the cost of goods and nothing extra.
2. Wide range of retailers
The network of stores that accept Affirm as a mode of payment is increasing with every passing day. Today, over 1,300 merchants list Affirm during checkout, and shoppers can even compare rates between different merchants if they want to buy a specific item.
3. No hidden fees
Loans from Affirm don't have any hidden fees. The loan repayment plan is transparent, and shoppers know the amount due every month at checkout. If you are late for a payment, Affirm won’t charge you any extra fees but will reduce your chances of qualifying for another loan.
4. Huge financing cap
Affirm can finance orders of up to $17,500. However, people qualify for different amounts, and not everyone can get this much. Depending on your individual determining factors, you should be eligible for a healthy amount to complete regular orders.
Cons of Affirm
Now, let’s look at a few cons of Affirm:
1. Variable APR
Affirm doesn't charge a fixed APR, and this can be a disadvantage. Shoppers don't know how much the loan will cost until they get to checkout. Even retailers that charge 0% APR do it on select items and not all orders.
Interest rates could go up to as high as 30%, which is no different from credit cards. For items that charge high interest rates, shoppers may be better off pursuing other choices.
2. Credit score checks
Among the main selling points of BNPL payment solutions is to give shoppers with bad credit scores a lifeline. Affirm doesn't dig deeply into one’s credit history but performs a soft credit check to determine how much a shopper qualifies for.
While other factors also come into play, the results from the credit check play a significant role. People with a bad credit history are bound to get low amounts or higher APRs, making the whole solution less suitable.
3. No reports for on-time payments
Affirm reports late payments to Experian credit bureau but won’t report timely payments. Shoppers are disadvantaged here since their timely payments aren’t being used to build their credit rating.
Can I use Affirm with discount codes and discounts?
Yes. You can get some percentage off your total amount due when applying coupons.
If you are looking for amazing coupons to use with Affirm and at retail outlets, check out Sacodes for amazing discounts and discount codes.
Here, you’ll find Affirm coupons and discount codes that you can use at checkout. It works no different from other coupons, as you'll find a discount code box at checkout where you enter the specific code and get the discount.
Not all of the coupons are universal, and you should check for restrictions to avoid any surprises during checkout.
Is Affirm right for you?
With all the rave reviews around Affirm and BNPL solutions, many shoppers are at crossroads on the best payment solution.
Affirm is ideal for you if you get a 0% APR. This is an unbeatable deal since you only pay for the item you buy but get the payment spread over a longer period. Some retailers like Nike, BedInABox, Adidas, Cricut, and Levi’s offer as low as 0% APR and are worth checking out.
The caveat is that the 0% APR doesn't apply to everyone and every item in the store, and you'll want to check if you qualify for it before completing the purchase.
If you want to fund a large purchase, Affirm is probably right for you. We all want to buy things at times and don't have the full amount to complete the purchase at that time. With Affirm, you can top up the amount you have with a loan and complete the purchase.
It's easier to qualify for a loan at Affirm than for a traditional credit card. Credit cards have more stringent requirements, specifically those pertaining to credit history, and those with bad history might not qualify. While Affirm performs a soft credit check, it also looks at other factors that might be in your favor and render you eligible for a loan with them.
You should avoid Affirm if you struggle to keep up with payments. This loan works for people who can make timely payments — for instance, formally employed people who are sure of getting paid during certain dates. If your income cycle is sporadic and you aren't sure when you'll get paid, avoid Affirm, as missed payments will mess with your credit history.
Affirm isn't an avenue for building credit. They don't report timely payments, and credit bureaus won’t recognize all your efforts. Consider other choices if you are looking for a loan to revitalize your credit history.
What are the top Affirm competitors?
Some notable players in the BNPL market space are:
Paypal’s Pay in 4
Pay in 4 is among the pioneers in this niche. The service is offered to millions of online merchants for transactions between $30 and $1,500.
To qualify for Pay in 4, shoppers must have a PayPal account that's linked to their bank or credit card account. Simply select it as the payment choice during checkout, and PayPal will take a few seconds to approve the purchase.
Payment is split into four installments where you pay a down payment during the point of purchase and spread the remaining balance.
Klarna
Klarna is a BNPL solution suited for huge orders. You can spread payments across months or even years. However, it only works for online orders.
Their first payment choice is similar to PayPal's, where the balance is spread out in four installments. This choice doesn't charge any interest.
For longer loans between 6 and 36 months, users have to create a virtual card on the Klarna platform and use this at checkout. The credit card is issued in partnership with WeBank and will accrue interest.
Afterpay
Afterpay is accepted by over 85,000 stores worldwide and works by splitting payments into four equal installments.
Its main proposition is applying smart credit limits to give shoppers loans that are within their means. No interest is charged for users who make payments on time. However, late payments accrue fees that can go up to as high as 25% of the original purchase amount.
There are no fixed minimum and maximum amounts you can borrow as it depends on the retailer and your credit history.
Splitit
Splitit works differently as shoppers don't have to sign up for any service. It uses your existing credit or debit card to split payments over an extended period.
When shopping, simply select it at checkout and key in your credit card details. There's no credit check, no interest charged, and no late fees.
The total amount is reduced as a pending transaction on your card. Every time a payment is due, the amount is charged on the card until all the payments are made.
Conclusion
Affirm is a top BNPL solution in today’s market, with over 7 million users and counting. It offers an easy way to spread out payments over an extended period and saves shoppers from spending too much on orders at one go.
To help reduce the cost of making orders and pay less, check out Sacodes for some amazing coupons and discount codes to use for these orders. Coupling them with a BNPL solution will help you to save even further.