Shopping
Understanding the New Walmart Buy Now Pay Later Plan Replacing Its Layaway Program — worth reading first
The COVID-19 pandemic affected shopper buying habits in many ways
Shoppers had to adjust to the new normal and make do with limited financial power compared to the pre-pandemic period.
With limited financial ability, shoppers resorted to alternative ways to complete orders. One way is by leveraging a Buy Now Pay Later loan in the market.
A recent survey shows that the number of shoppers applying a Buy Now Pay Later plan increased from 37.65% in July 2020 to 55.8% in March 2021. Projections indicate that this industry, which was worth a few million dollars in 2021, is expected to grow by 1200% by 2024.
Buy Now Pay Later solutions give shoppers a way of paying for orders in installments without having a credit card.
Walmart, among the leading retail outlets globally, has a popular Buy Now Pay Later (BNPL) plan. This article will break down the nitty-gritty of this plan, explain how it works, and help you determine if it works for you.
What is Walmart Buy Now Pay Later?
Long before the introduction of BNPL loans, assorted retailers had layaway plans, mostly during the holiday season.
(Image source)
They were initially designed during The Great Depression when people didn't have enough money to make full payments for items. Shoppers could pay for goods in installments spread over a specific period and then collect them when they cleared the balance.
However, the adoption of credit cards in the 1980s and 1990s offered shoppers a better solution, and layaway plans declined.
Walmart offered shoppers a layaway program until before the 2021 holiday shopping season. At this point, they scrapped it and referred shoppers to their new BNPL plan in partnership with Affirm.
Their layaway plan was interest-free. However, shoppers had to clear the balance before picking up the item they were paying for.
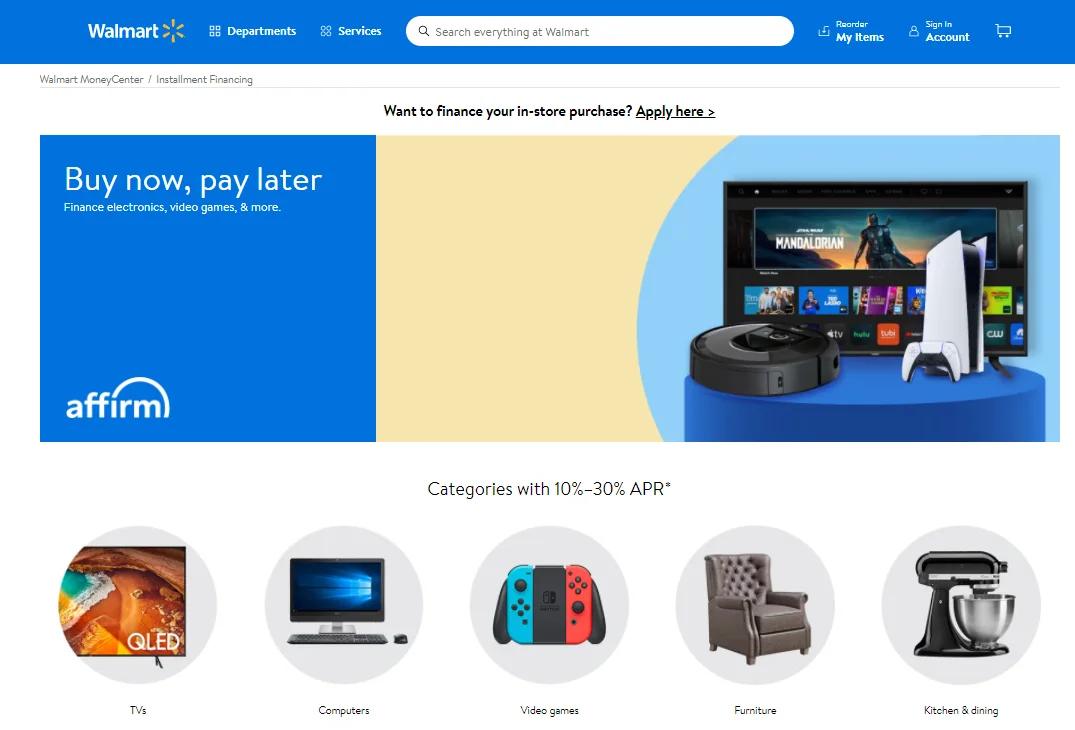
This is what the new Buy Now Pay Later Plan tries to fix. This alternative to layaway allows you to pick up the items and pay the balance in installments. However, interest rates range between 10% and 30% depending on a mix of factors.
While layaway was a great way for shoppers to reserve holiday items, Walmart’s BNPL plan is the future. It increases a shopper’s choices, especially for those who don't have access to credit facilities and cannot complete payments in one instance.
Besides, our recent survey indicates 72.6% of shoppers added items to their cart or bought something that costs more because of their encounter with a BNPL choice. This shows how this solution empowers shoppers to make larger orders at retailers like Walmart.
With a clear understanding of how the plan works and what interest rates a shopper is charged, anyone can use Walmart’s BNPL to finally make those huge orders and pay for them as time passes.
How does the Walmart Buy Now Pay Later Plan work?
Shoppers can choose between four BNPL plans when shopping at Walmart. However, Affirm is Walmart’s official partner and the primary one offered at their retail channels.
While choosing the primary choice is ideal, don't restrict yourself to it as the other plans might offer better terms. Always check out the APR, repayment period, and cost of taking up the loan with all the offered choices before signing up for one.
Here, we’ll break down how Walmart’s Buy Now Pay Later plan works for the four businesses offered to shoppers.
Affirm
Walmart lets shoppers buy items and pay for them in easy and low-priced payments spread between three and 24 months.
The plan is transparent, and shoppers know the exact terms, if eligible, at the point of purchase. APRs are different for every item, and this is displayed before you confirm the payment. This way, you'll know the total interest and monthly installment to be paid, things that are fixed throughout the payment period.
Affirm doesn't charge any fees to open an account, for prepayment, or for late payments. However, late payments are reported to Experian Credit Bureau and will affect your eligibility for the next loan you apply for with Affirm. As such, it is in your best interest to be sure that all installments are paid in good time.
For online orders, simply select Affirm as a payment method at checkout on Walmart.com. The page will link to your account on Affirm, and do a quick check to see if you are eligible. It'll show the applicable APR for the items you're buying and the period you'd want to pay it.
Select the number of months you want to spread the payment through and confirm to complete the purchase.
For in-store orders, apply for the loan at affirm.com/walmart and pick a suitable payment plan. When you get to the POS system, scan the one-time use barcode, and the payment will go through.
Loans for goods worth between $144 and $800 are to be paid in 12 months, while those above $800 going to $2,000 can be paid in up to 24 months.
You can buy some promotional items at Walmart with 0% APR. Here, you pay no interest and simply spread the item’s payment over an extended period.
Zip Pay
Zip Pay is a BNPL service that lets shoppers shop at Walmart and pay in installments applying their platform.
It splits payments into four installments spread across six weeks.
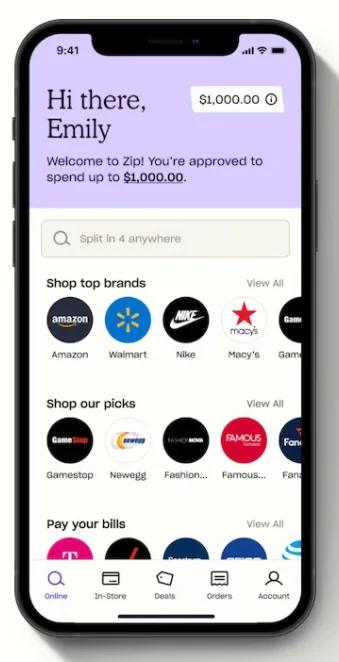
To use it, first, download the Zip Pay App. Since it isn't the official Walmart BNPL partner, you have to go through its app, contrary to the case with Affirm.
(Image source)
On the Zip App, select Walmart from the list of offered retailers and proceed to shop. It'll direct you to Walmart’s catalog and choose the items you want to buy. On completion, proceed to the payment page to check out the details of the six-week repayment plan.
Zip’s loan is powered by VISA and at this stage, it'll generate a single-use virtual card with a credit card number, CVC, and expiry date. Use this to complete the payment at Walmart’s checkout page.
For in-store orders, use the virtual card to pay at the virtual NFC terminal. Loans are offered for up to $1,000. However, the account accrues $6 per month as a facilitation fee.
Klarna
Klarna is similar to Zip Pay since it generates single-use credit cards that you use to check out at Walmart.
It all starts at the Klarna App — where you need to create an account and select Walmart from the list of retailers.
Pick the items, and on checkout, the app will show the repayment plans. With Klarna, you have to pay back the full amount in four installments separated by two weeks each.
If the plan is good for you, generate a virtual credit card that you'll use at checkout. Note that the credit card is offered in partnership with WeBank, and there’s a slight overcharge to facilitate its usage.
Feel free to learn more about Klarna’s BNPL solution here.
PayPal Pay in 4
Pay in 4 is a BNPL plan by PayPal. It's offered to users who hold a PayPal account in good standing.
(Image source)
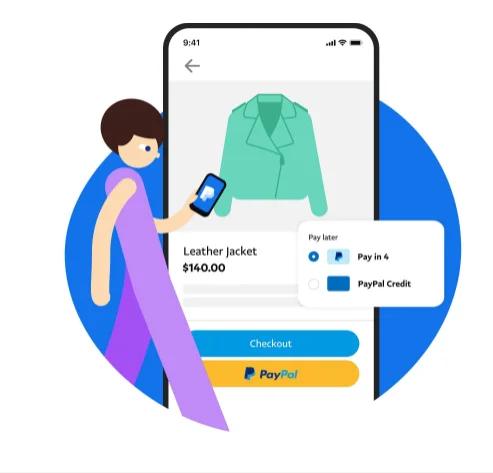
It's among the BNPL choices offered to Walmart shoppers. To use it, select PayPal as a checkout choice at walmart.com. Rather than paying the amount, select Pay Later, and let the platform check your eligibility.
PayPal runs a soft credit check on you, and the decision is returned in seconds. If your loan request is approved, proceed to checkout, and the payment will be complete.
Pay in 4 splits the total amount into four interest-free payments. However, the plan charges late fees if you don't repay an installment on time. The first installment is due at the time of purchase and the following two weeks after.
You can use it for orders between $30 and $600 at Walmart.
What items can you buy with the plan?
Walmart’s BNPL plan is limited to eligible categories, including —
- TVs
- Computers
- Video games
- Furniture
- Toys
- Smartwatches
- Tablets
- Kitchen and dining equipment
- Floorcare equipment
- Sports and outdoor equipment
- Jewelry
- Baby items
- Apparel
- Art and Crafts
Ineligible categories include —
- Alcohol
- Gasoline
- Personal care items
- Baby consumables
- Groceries and food
- Miscellaneous supplies
- Pest supplies
- Pharmacy, health, and wellness
- Tobacco
- Temporary specialty items
- Weapons
- Wireless service plans
Is the Walmart Buy Now Pay Later plan for me?
Walmart’s BNPL plan isn't perfect. It has its good and bad when compared to other types of loans.
The best way to buy any item is to pay for it upfront, but it isn't always easy, especially for orders that require large sums.
Depending on which provider you choose to go with, Walmart’s BNPL plan can affect your credit score. These providers don't report timely payments but will report late payments. Be sure that you have the money to pay the balance in time.
Consider other choices if your income is sporadic and you cannot point to a date where you'll have the money to pay an installment.
Walmart’s BNPL solution is ideal for anyone with a regular income stream, as they are sure of paying back the balance within the stipulated time.
Conclusion
Walmart’s Buy Now Pay Later plan is a great alternative to the layaway program that had been in place for many years. While it works differently, it offers shoppers a huge benefit — they can take the item and pay for it as time passes.
Before buying any item at Walmart applying their Buy Now Pay Later plan, learn which of the four service providers give you the best terms. Look at the repayment periods, and settle on one that suits you perfectly. The goal here is to avoid any late payments that can incur charges or affect your credit score, so find one that works for you.
If you are looking to pay less for items, check out Sacodes for coupons that you can redeem at a wide variety of retailers. You can single out Walmart coupons and couple them with a BNPL plan to help you pay less and save some money.
Topics Credit